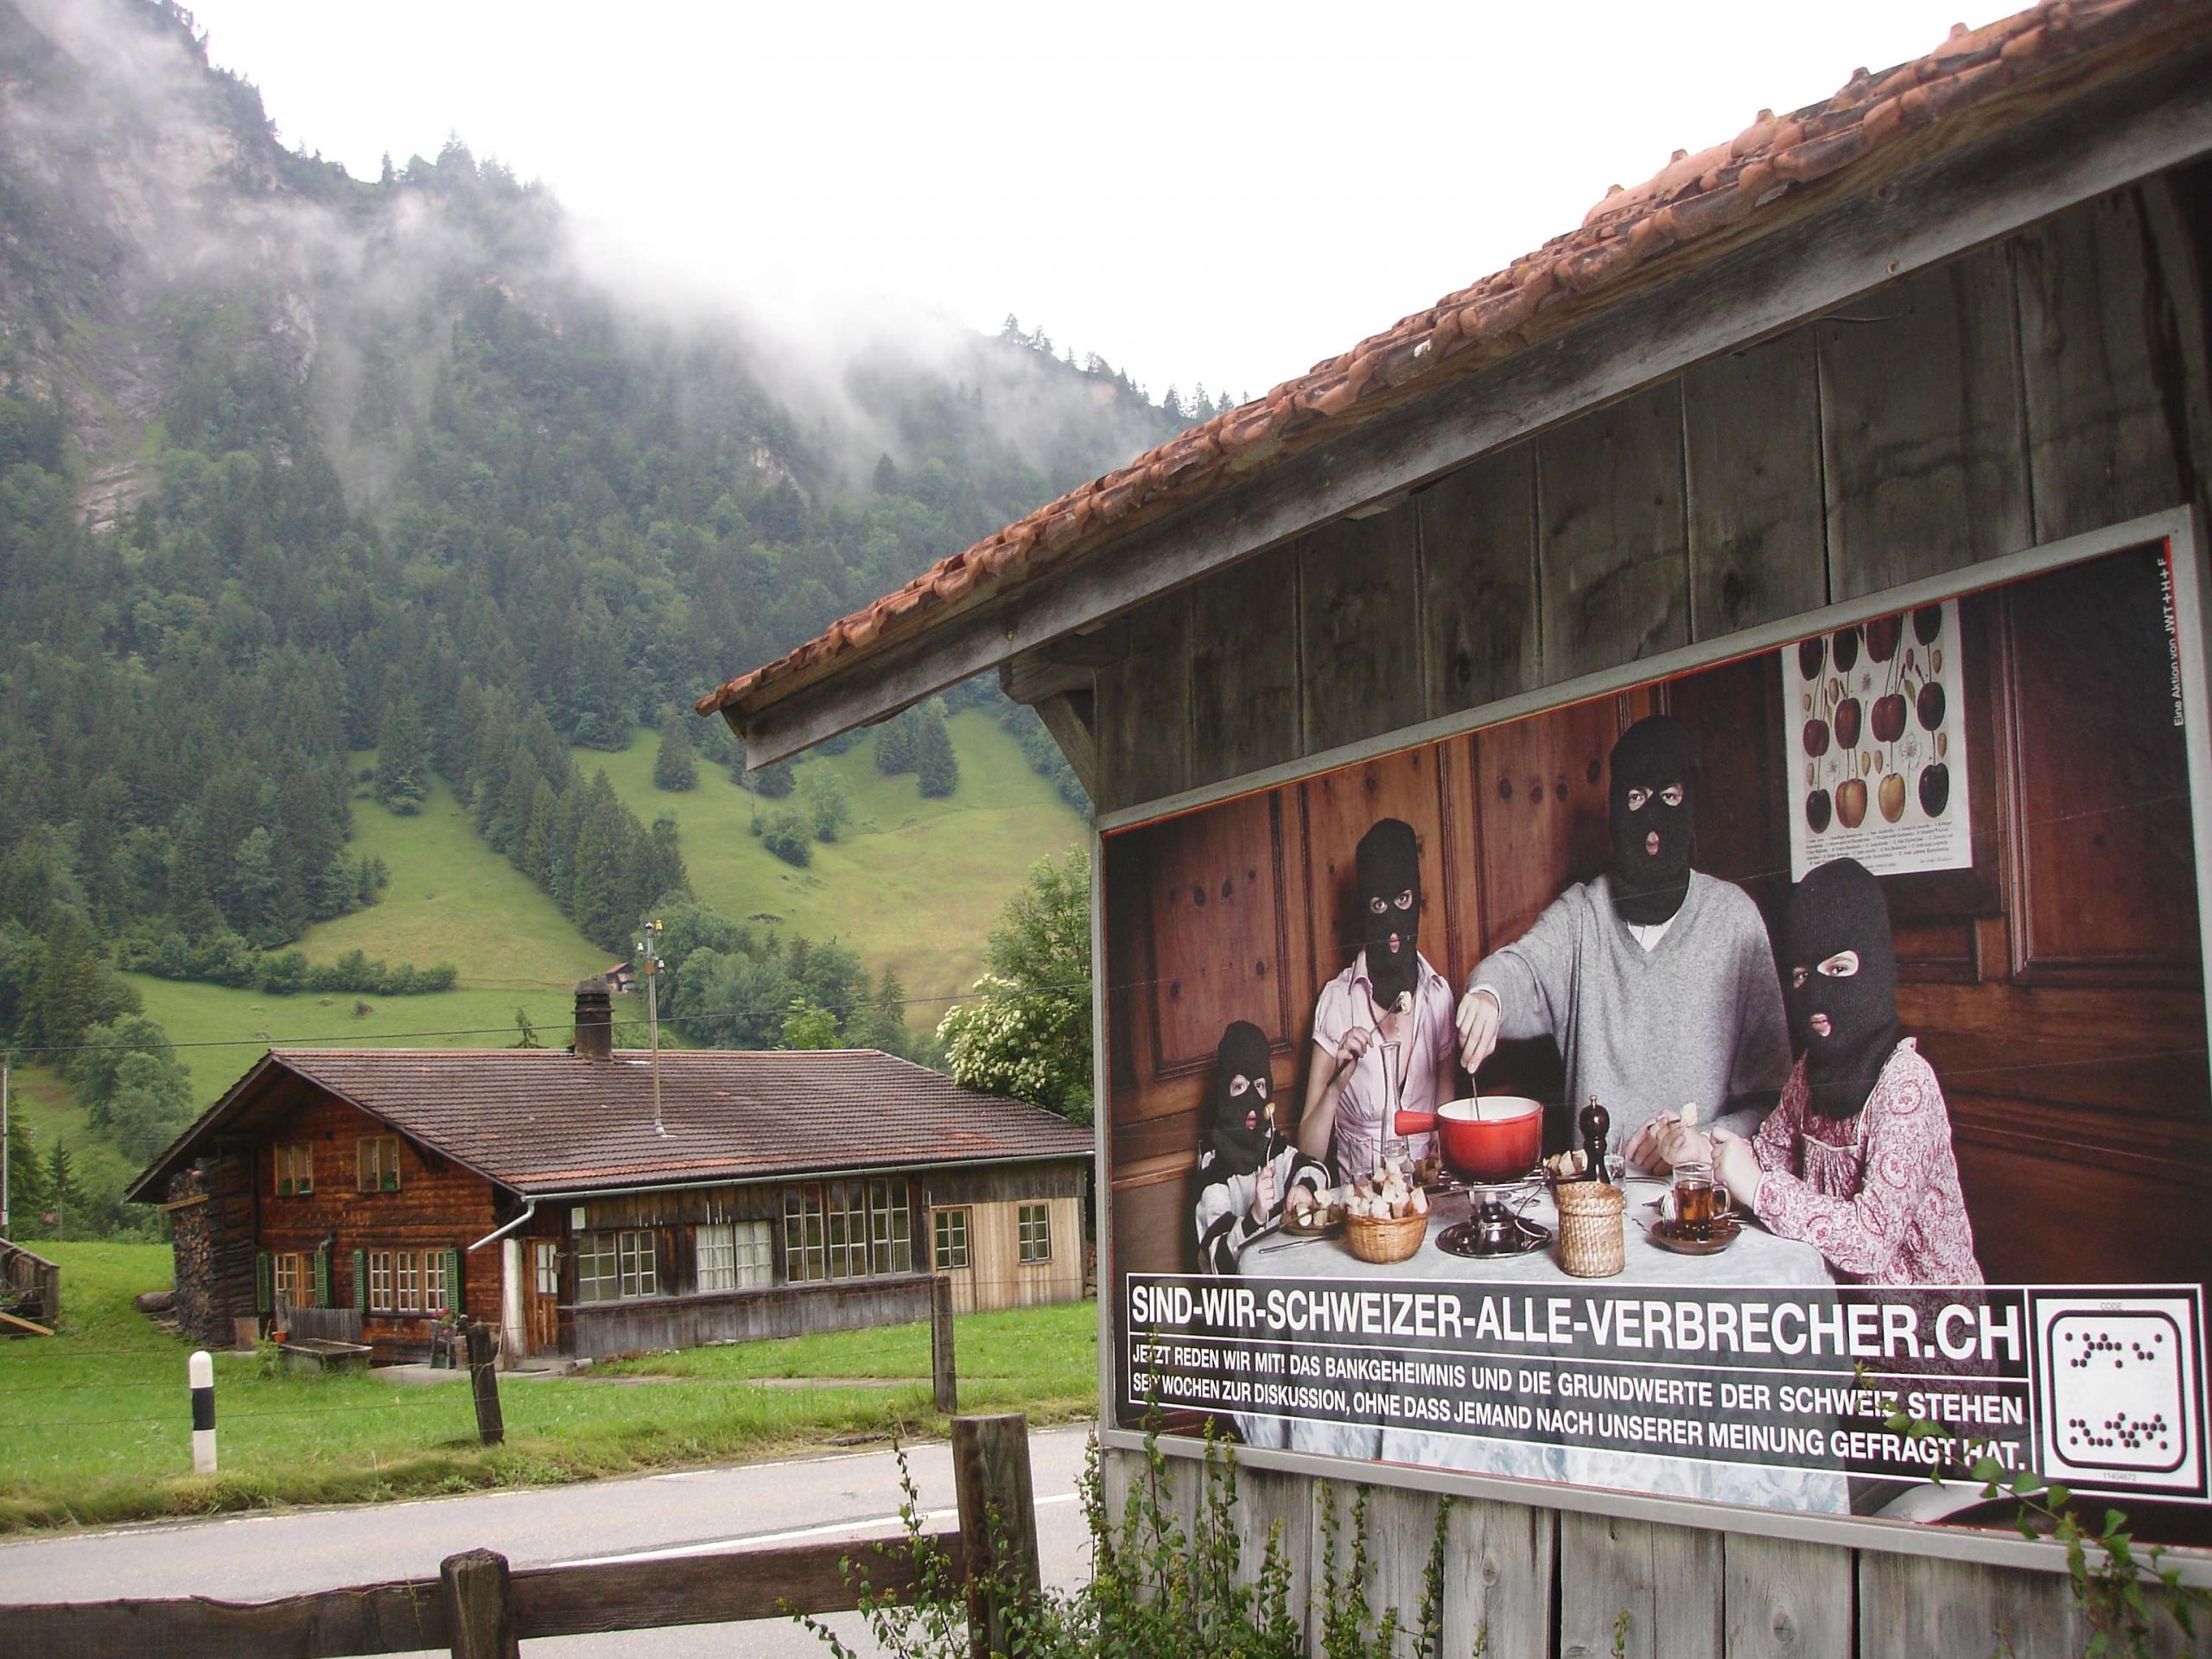
“Are we Swiss all criminals?” The poster asks. No. But many Swiss bankers are.
We have written recently about how Credit Suisse’s $2.6 billion fine for its history of abusing the U.S. tax system and facilitating high crimes may seem like a lot of money, but it could — and should — have been a lot worse. Why did no bankers go to jail? And, perhaps more importantly, why does it still have its U.S. banking licence?
But there has been a palliative, it seems: according to reports:
“As part of its plea agreement, Credit Suisse agrees to forego any kind of tax deduction for any of the payments it makes.”
Which is fine and dandy — good, in fact, as far as it goes. But now, from the Swiss newspaper Le Matin:
“During the UBS scandal, the debates raged in parliament. Then, nothing happened. Or, in fact, a majority of the parties on the right (UDC and PLR) buried the idea of preventing the fines to be deductible from their profits (for tax purposes.) The result is that the record fine that Credit Suisse has just been hit with in the United States (US$2.6 billion) may be deductible after all.”
In other words, U.S. taxpayers won’t be sticking with the bill, but CS may well foist it on ordinary Swiss citizens instead. Let’s see what happens: the outcome is currently uncertain.
If it ends up being tax-deductible, one may conclude that this is poetic justice of a kind, given Switzerland’s role as a large, mucky tax haven. And it will doubtless infuriate many ordinary Swiss people, being stuck with part of the bill for all this criminality: this will doubtless provoke debate and reflection in Swiss society, which is much needed. If truth be told, we don’t have a beef with ordinary Swiss taxpayers: it’s the jurisdiction and its tax and secrecy laws that bother us.
And besides, the United States is hardly one to talk about being a tax haven.
Hat tip: James Henry.
The author

Related articles
UN tax convention hub – updates & resources
UN Framework Convention – Roundup of the Fifth Session of Negotiations
Notes on the UN tax convention draft protocol on dispute prevention and resolution
11 September 2026
The European Court of Justice strikes against transparency again. Our response should be to call for an end to corporate limited liability
Report of the Fifth Session of negotiations on the UN tax convention
4 September 2026
Submission to Workstream I on Co-Lead’s Zero Draft of UN Framework Convention on International Tax Cooperation (post-Fifth Session)
28 August 2026
Submission to Workstream II on Taxation of Income from Cross-Border Services (post-Fifth Session)
26 August 2026
Strengthening public resource mobilization through tax justice
25 August 2026
Submission to Workstream III on Dispute Prevention and Resolution (post-Fifth Session)
24 August 2026
From data to policy: Building Africa’s evidence ecosystem for better tax reform